MEMBER NEWSLETTER
|
APRIL 2026
How lower MER can help your savings blossom
As spring brings fresh starts and warmer days, it’s the perfect time to pause and check in on your retirement savings.
We’re here to make sense of pension plan expenses and show how understanding them can help you get the most out of every dollar you’ve set aside. After all, a little clarity now can help you make choices that let your savings grow in the seasons ahead.
Understanding your pension plan costs
When saving for retirement, costs matter. That’s why SPP uses one simple measure – the Management Expense Ratio (MER) – to explain the total cost of running the plan.
The MER includes all costs associated with administering the plan and managing investments. Our goal is straightforward: keep costs low so more of your money stays invested.
SPP targets an MER of less than 1%.
WHAT IS MER?
The MER is the cost (as a percentage of a fund’s assets) to run the plan and manage your investments. This includes activities such as:
  • Professional investment management
  • Pension plan administration
  • Record-keeping and member services
  • Plan operations and governance
The MER is automatically reflected in investment returns. There are no separate charges.
WHAT MER IS NOT
SPP is a not‑for‑profit plan. Funds are offered directly to members, so there are no sales charges, commissions, or advisor costs. There’s no cost to join.
HOW DOES SPP CALCULATE MER?
We strive to keep MER as low as possible, which means strictly managing our yearly operating expenses.
The expense amount is then divided by the average of the opening and closing asset values held by all of our members, which gives us a Management Expense Ratio percentage.
SPP targets an MER of less than 1%.
WHY MER MATTERS
A lower MER helps your savings grow over time. Even small differences in costs can add up. For example, investing $10,000 for 30 years:
  • 1% MER: about $33,000*
  • 2% MER: about $24,500*
That means $8,500 less for you due to higher costs.
* For illustration only; assumes 5% annual growth before charges.
LOW COSTS, BEFORE & AFTER RETIREMENT
Whether you’re contributing or receiving VB income, a lower MER means more of your money stays invested, helping your retirement savings last longer.
Easy ways to contribute
With SPP, you’re in control. Contribute as much as you choose, within your RRSP limit**. Add to your savings when and how it works for you!
Online, in person, or by mail.
Set up automatic contributions for peace of mind.
Contribute via online bank bill payment.
You can also transfer in from unlocked registered investments held elsewhere.
Transfer-in
Maximizing your contributions helps you take full advantage of the strong performance and low MER of SPP, so your nest egg can grow even bigger over time!
Choose Your Contribution Method
** Must have available RRSP room. Funds are locked-in until age 55.
Updates from your SPP team
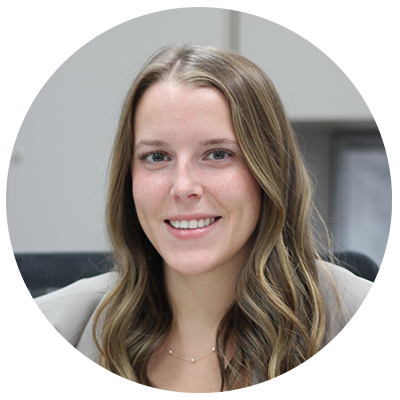
Madison Kosolofski promoted to Senior Financial Investment Officer
Born and raised in Kindersley, Sask, Madison joined SPP in May 2024. With a Bachelor of Commerce in Accounting, she brings a solid background in accounting principles, investment analysis, and financial decision-making.
Madison is proud to support SPP’s work and looks forward to growing with the team in her expanded role.
Get in touch with us!
Questions about your pension or want to know more about SPP? We’re here to help!
Follow Us
Contact Us
1 (800) 667 7153
info@saskpension.com